Unsold stock given to charity: no VAT charge since April
Since 1 April 2026 VAT-registered sellers can give stock to charities to pass on, with no VAT charge on items worth £100 or less. What counts.
22 October 2026 · 4 min read
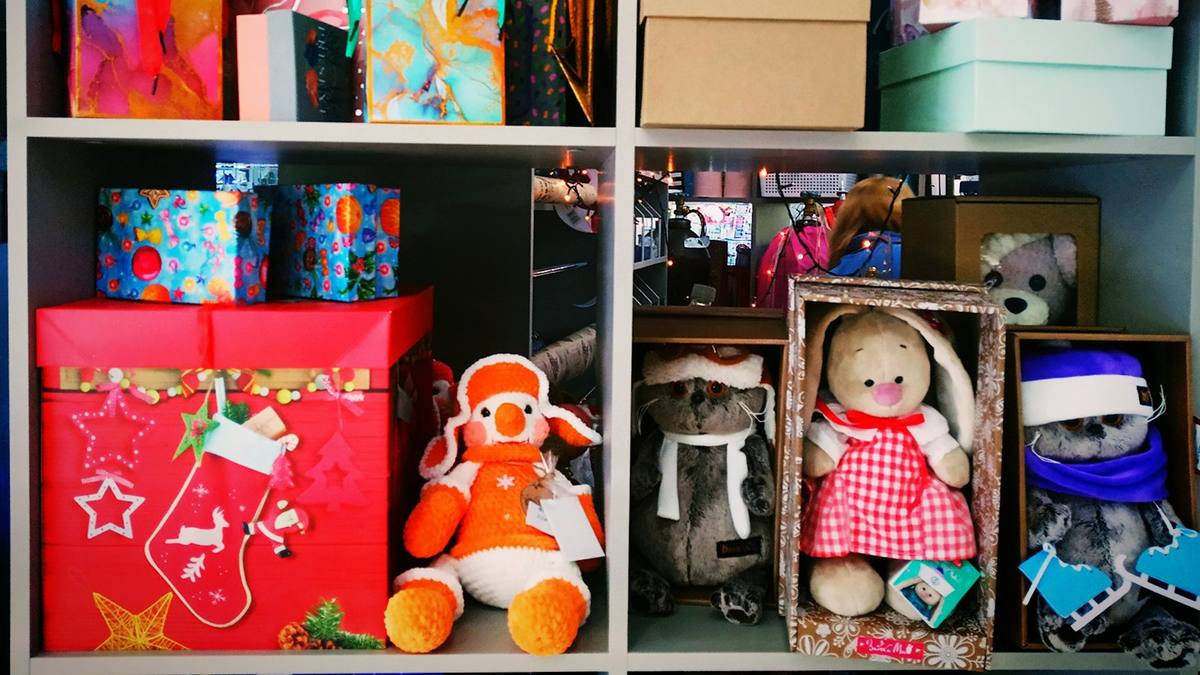
Since 1 April 2026, a VAT-registered seller can give unsold stock to a charity to pass on to families, or to use in its non-business charitable work, without paying VAT on the gift. The relief covers items worth £100 or less each, or £200 for some household goods, and for the right charity it applies to toys, clothes, toiletries and most of what sits unsold in a stockroom in October.
Before April, giving stock away usually meant accounting for VAT as if you had sold it, if you had reclaimed the VAT when you bought it. So a seller who donated £3,000 of unsold goods could owe HMRC VAT on goods that earned them nothing. That trap has gone for most donations to charity, and winter appeals across London are about to start asking.
Two kinds of donation
HMRC's VAT Notice 701/1 now splits charity donations of goods two ways.
Goods given to a charity, or its trading company, to sell in its shops have been zero-rated for years. That still applies, with no value limit.
The new relief is for goods given to a charity to hand on to an individual, another charity or another organisation, or to use in its non-business activities. A toy appeal that gives presents to children, a baby bank, a winter coat drive: these are onward donations, and since 1 April they carry no VAT charge for the donor.
What counts, and the limits
The limit is per item, and an item means the thing a shopper would buy, not the pallet. HMRC's own example is a pallet of 100 bottles of shampoo: each bottle is an item.
Most goods qualify up to £100 an item. A higher £200 limit applies to household appliances, furniture and mattresses, flooring, computers and tablets, and mobile phones. Alcohol, tobacco and vaping products are excluded.
The value is the lower of what the item cost you and what it would cost to buy an identical one now, in its age and condition, both excluding VAT. For old stock that has lost value, the second figure is usually the lower.
The charity must be registered with the Charity Commission or the equivalent regulator, or with HMRC for tax purposes. Community interest companies are not charities and are not covered.
The paperwork HMRC expects
You are the one claiming the relief, so you keep the evidence. HMRC expects a document from the charity with its name, address and registration number, and a signed statement that the goods will be passed on or used in its non-business activities. For regular donations, an annual update is enough.
On your side, keep a description and quantity, the cost or value, the date, and proof the goods reached the charity, such as a signed delivery note.
Illustration, not a real client: a VAT-registered seller in Croydon has 400 children's craft kits left from last Christmas. They cost £6 each before VAT, and an identical kit would now cost about £4. She gives them to a registered charity running a Christmas toy appeal in south London, which signs a statement that they will go to families. Each kit is valued at £4, well under £100, so there is no VAT on the donation. Before April, having reclaimed the VAT when she bought them, she would have had to account for VAT on them.
Income tax and Corporation Tax
The direct tax side was already generous. HMRC's Business Income Manual says that when a trader gives trading stock to a charity, "no amount is brought into account as a receipt", so the cost of the goods stays deductible in full. It applies automatically. The exception is where you, or someone connected to you, get a benefit in return, which is then taxable.
So a donation does not have to be booked at its sale value. The stock simply leaves the books at cost, and the cost stays a cost.
Before the appeals open
Go through what will not sell before the Christmas stock arrives. For the VAT limit, value each item at the lower of what it cost you and what an identical one would cost now. Your accounts use a different test, and our guide to valuing stock at the year end covers it. Then pick a registered charity, ask it for the signed statement first, and keep a delivery note.
Stock that will not sell costs money to store. Since April, giving it to the right charity no longer costs VAT as well.
About the author
Harvey Dhillon is Founder and CEO of Zmartly, a UK accountancy firm for ecommerce sellers. He grew up in West London and began his career in investment banking finance at Barclays, before going full-time on Zmartly in 2020. He is a Chartered Management Accountant (ACMA, CGMA).
Featured photo by Dmitry Burdakov on Unsplash.
Contributor at The London News